Let me say the thing nobody in my business wants to say out loud: the perfect time to buy is not coming. There's no text message you're going to get. No news alert. No magic week where rates are low, prices are soft, and nobody else is shopping. If you're waiting for that, you're going to wait yourself right out of the market.
I'm not saying that to scare you into a house. I make money whether you buy today or next year, so I've got no reason to rush you. I'm saying it because I watch people do this every single month here in the Inland Empire, and it costs them.
Here's the myth. "Rates are too high. I'll wait for them to come back down, then I'll buy." Sounds smart. Feels responsible. And on paper, it makes sense — the 30-year fixed is sitting around 6.49% right now (that's the Freddie Mac average as of late June). A year ago it was 6.77%, so it's actually drifting the right direction. So why not wait?
Here's what nobody tells you. Most people only ever talk to one side of this. You've got a Realtor who knows houses, or a loan officer who knows rates — and each one only sees half the board. I'm both. I'm a licensed real estate broker and a mortgage broker. So let me show you the whole board.
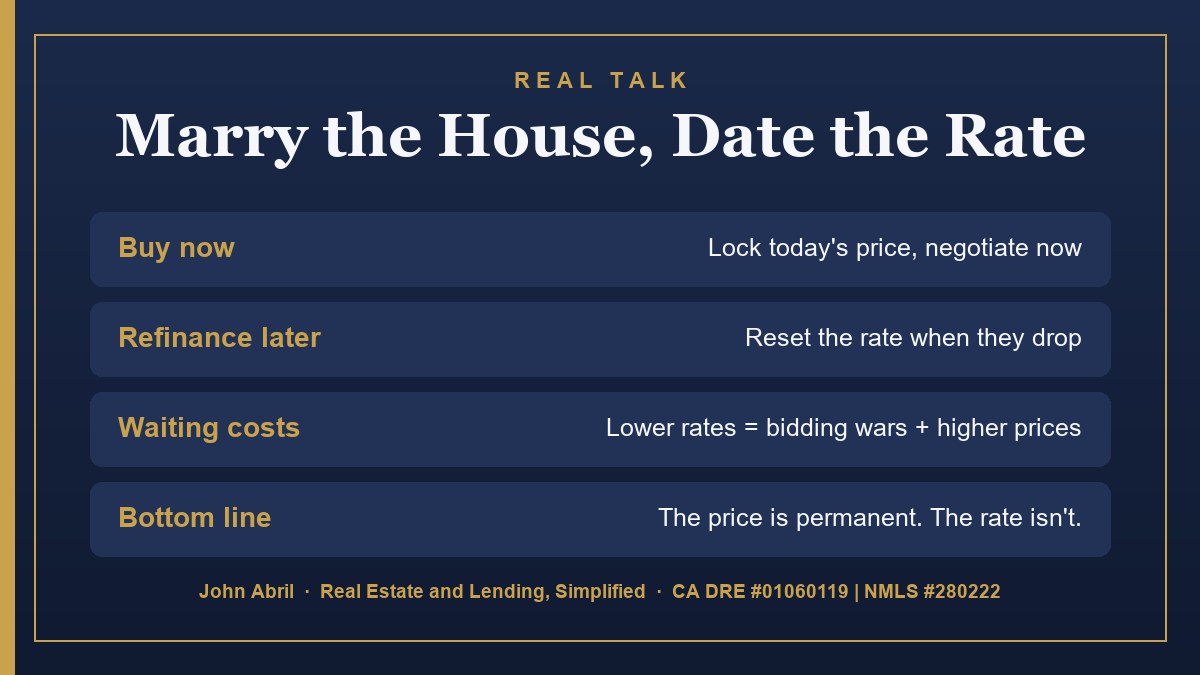
When rates drop, you don't get a deal. You get a bidding war. Every buyer who was sitting on the sidelines with you comes flooding back at the exact same time. The house that nobody wanted at 6.5% now has six offers at 5.5%, and the price jumps to cover it. You waited for a lower payment and the market handed you a higher price and zero negotiating room. I've seen buyers "save" one percent on their rate and lose it all — and then some — on the purchase price.
Now the math, because real talk needs real numbers. Take a $500,000 loan, rough example, not counting taxes and insurance:
- At 6.5%, your principal and interest run about $3,160 a month.
- At 5.5%, that drops to about $2,840 — roughly $320 a month lighter.
That $320 is real money, I'm not going to pretend it isn't. But here's the move most people miss: you don't have to choose. You can buy the house now, at today's price, while you still have room to negotiate — and then refinance into that lower payment later, when rates actually drop. You lock the price today and you reset the rate tomorrow. You marry the house and you date the rate.
Let me keep it honest, though, because that's the whole point of Real Talk. A refinance isn't free and it isn't instant. There are closing costs. There's a seasoning window — you generally need a stretch of on-time payments before it makes sense, and I won't refinance you into something that costs you more than it saves. I'll run the actual break-even with you before you spend a dollar. Some people the refi makes obvious sense; some it doesn't. That's a conversation, not a sales pitch.
And buying isn't right for everyone right this second, either. If your job is shaky, if you'd be scraping the bottom of your savings to close, if you might move in two years — wait. Renting while you get solid is a perfectly good decision. I'll tell you that to your face even though it means I don't get paid. That's the difference between somebody selling you a house and somebody actually advising you.
Here's what I'd tell my own family. Stop trying to time the bottom — nobody catches it, not even the pros. Figure out what you can actually afford on today's numbers, not the fantasy rate in your head. Get a real Loan Estimate so you're working with facts instead of vibes. And if the payment works for your life today, the rate is a problem you can fix later. The price is not.
The people who built wealth in real estate in the IE didn't do it by waiting for the perfect week. They did it by owning the asset and letting time do the heavy lifting.
If you want to know what your actual numbers look like — not a guess, the real thing, the house and the loan from one person who sees both — call me. Worst case, I tell you to wait, and you walk away with a plan.
Rates and terms subject to change without notice. Examples shown are illustrative and not a commitment to lend; your actual rate and payment will vary based on credit, down payment, and property. All loans subject to credit approval. John Abril — CA DRE #01060119 | NMLS #280222.