Every single week, somebody asks me some version of the same question: "John, isn't the market about to crash like 2008?" Prices are high, rates are high, the news feels grim — so people brace for a repeat of the meltdown that wiped out a generation of homeowners.
I get why the fear is there. But I read loan files all day and I see what's actually selling out here, and I'm going to give it to you straight: what we have today is not 2008. Not even close. Let me show you why, because once you understand the difference, you stop making decisions out of fear.
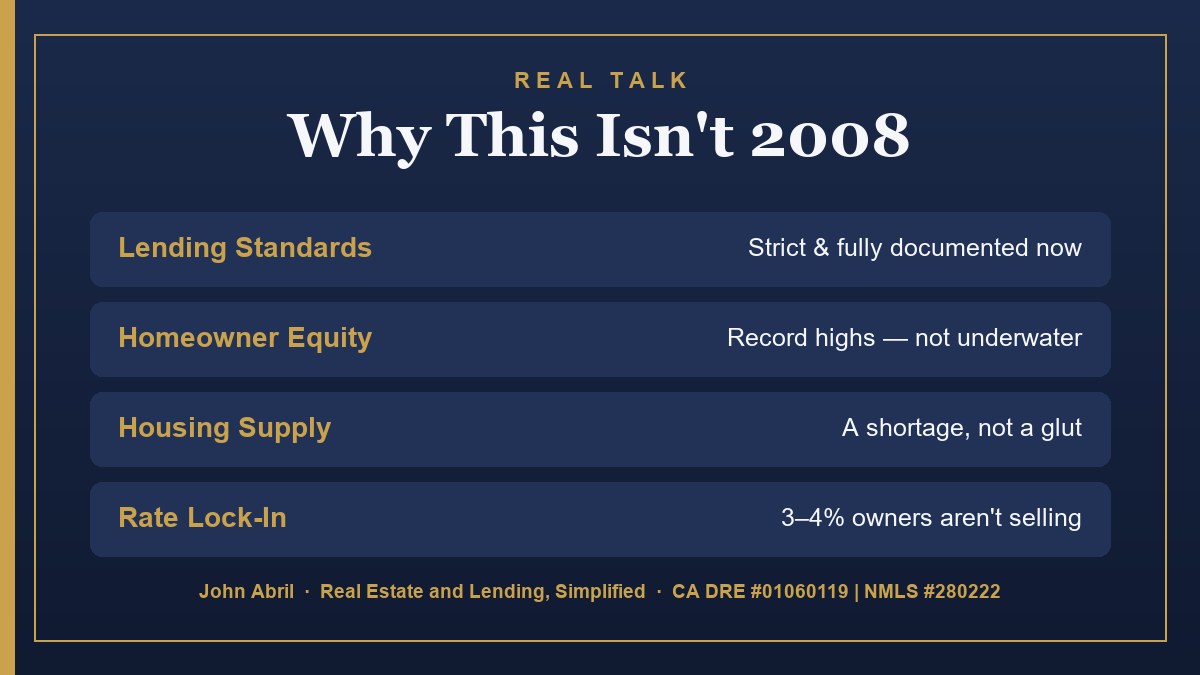
Reason 1: Nobody's getting loans they can't afford anymore. The 2008 crash was built on garbage loans — no income verification, no down payment, "liar loans," teaser rates that exploded two years later. People got handed mortgages they had no business getting. After the crash, the rules changed completely. Today, I have to document everything — your income, your job, your assets, your ability to actually repay. The buyers closing right now are qualified. That alone removes the fuel that lit the 2008 fire.
Reason 2: Homeowners have equity now, not negative equity. In 2008, millions of people owed more than their house was worth. The second things got tight, they walked away, and that flood of foreclosures crushed prices. Today is the opposite. Homeowners are sitting on record equity — baby boomers alone hold around $19 trillion of it. When people have real equity, they don't get foreclosed into the street; they have options. No equity, no forced selling. No forced selling, no 2008.
Reason 3: We don't have too many houses. We have too few. 2008 was a glut — builders had massively overbuilt and there were way more homes than buyers. Right now it's the exact reverse. The whole country, and the Inland Empire especially, is short on housing. You can't crash a market from oversupply when there isn't any oversupply. Tight supply puts a floor under prices.
Reason 4: The "lock-in" effect nobody talks about. Most people who own a home right now have a mortgage in the 3% to 4% range. They are not about to sell a 3% loan to go buy something at 6.5%. So they stay put. That keeps even fewer homes on the market, which — you guessed it — supports prices instead of sinking them.
Now let me keep it honest, because that's the whole point of Real Talk. "Not 2008" does not mean prices only go up forever. Some overheated markets are cooling off. Prices in the IE could flatten, and in some pockets they could dip. That's normal. But a flat year or a small dip is a completely different animal than a 30%-to-50% collapse. A collapse needs a wave of people forced to sell all at once — and the four things above are exactly why that wave isn't coming.
So what does this mean for you? Two things. One: stop bracing for a crash that the fundamentals don't support — you'll "wait for the deal" right past your window, the same way the rate-waiters do. Two: don't let me talk you into buying out of FOMO either. The right move isn't fear or hype. It's looking at your real numbers — your income, your job stability, your savings — and deciding what works for your life.
Here's my edge, and why I can say all this with a straight face: most people only see half the picture. A Realtor sees the listings. A loan officer sees the financing. I'm both, so I see who's actually qualifying and what's actually selling. When I tell you the floor is holding, it's because I'm watching both sides of the deal every day.
If you want to talk through what today's market means for your situation — buying, selling, or just trying to make sense of the noise — call me. No fear, no hype, just your real numbers.
This is general information, not financial advice, and not a commitment to lend. Market conditions vary by area and over time; past performance is not a guarantee of future results. All loans subject to credit approval. John Abril — CA DRE #01060119 | NMLS #280222.